Kaplan Fox Shareholder Alert: Bloom Energy (NYSE: BE) Faces Securities Fraud Class Action Over Alleged Undisclosed Chinese Scandium Sourcing
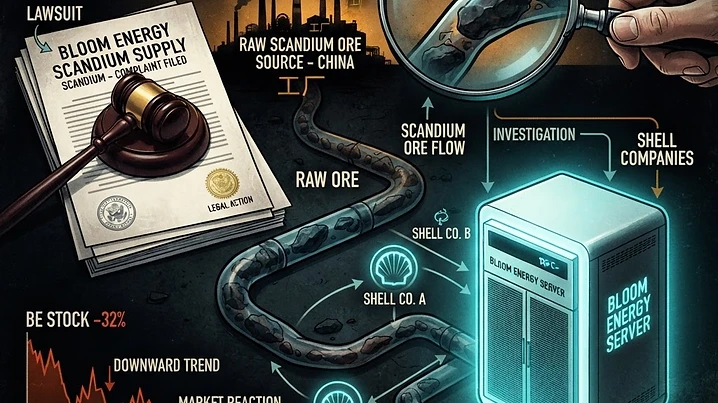
Kaplan Fox & Kilsheimer LLP has issued a shareholder alert reminding investors of the September 28, 2026 lead-plaintiff deadline in a securities fraud class action filed against Bloom Energy Corporation (NYSE: BE). The complaint alleges that Bloom Energy understated its reliance on Chinese-sourced scandium obtained through intermediaries — a material supply-chain dependency the plaintiffs say was concealed from investors despite being load-bearing for the company's clean-energy production model.
Epistemic note. A class action complaint contains allegations that have not been adjudicated, tested in court, or admitted by Bloom Energy Corporation. The Forensic Ledger is reporting on the existence and substance of the filed complaint and shareholder alert, not adopting its allegations as established fact. Bloom Energy is entitled to dispute the claims, and the outcome of the litigation is uncertain.
The scandium dependency at the core of the thesis
Scandium is a critical input for Bloom Energy's solid oxide fuel cell technology, and the security and transparency of its sourcing is directly relevant to the company's production economics, geopolitical risk profile, and compliance posture. The class action centers on what Bloom told investors about its scandium supply chain — and what the plaintiffs allege was concealed. According to the complaint, the company understated its reliance on Chinese-sourced scandium obtained through intermediaries, a structure that, if true, would obscure both the true origin of a critical input and the concentration of supply-chain risk in a single jurisdiction.
Why intermediary sourcing is load-bearing
The use of intermediaries to source a critical mineral from China is not a neutral logistical detail. It bears on tariff and trade-policy exposure, sanctions and export-control risk, and the credibility of any "secure supply chain" narrative the company may have presented to investors. If, as the plaintiffs allege, Bloom's actual reliance on Chinese-sourced scandium was materially greater than disclosed — and was routed through intermediaries in a way that obscured that reliance — then the risk profile investors had priced was structurally different from the one they were told about. A single-jurisdiction dependency on a critical input, concealed behind intermediary layers, is precisely the kind of disclosure gap that securities class actions target.
The September 28, 2026 lead-plaintiff deadline
Kaplan Fox's alert flags the September 28, 2026 lead-plaintiff deadline for investors wishing to seek appointment as lead plaintiff in the class action. The deadline is a procedural milestone under the Private Securities Litigation Reform Act, and its public circulation often correlates with expanded media coverage and additional claimants joining the putative class — developments that can shape the trajectory and settlement posture of the litigation even before any merits ruling.
What would falsify the plaintiffs' thesis
Falsification would look like: Bloom demonstrating that its scandium sourcing disclosures were accurate and complete, with any reliance on Chinese-sourced material obtained through intermediaries properly disclosed or immaterial to the company's risk profile; the class action being dismissed or settled on terms that do not materially impair the business; and the company demonstrating diversified, secure scandium sourcing that does not concentrate risk in a single jurisdiction. Corroborating developments for the plaintiffs would include disclosures of greater-than-represented Chinese scandium reliance, regulatory or customs scrutiny of the intermediary sourcing structure, supply-chain disruption tied to the alleged dependency, additional class actions or derivative suits, or restatements of supply-chain-related disclosures.
Source
⚖️ Editorial Disclaimer
This article is original reporting by The Forensic Ledger Desk on a publicly filed securities class action complaint and an associated shareholder alert. A complaint contains allegations that have not been adjudicated, tested in court, or admitted by Bloom Energy Corporation. The Forensic Ledger is an independent newsroom and does not adopt the plaintiffs' allegations as established fact; Bloom Energy is entitled to dispute the claims, and the outcome of the litigation is uncertain. This article is published for informational and journalistic purposes only, is not investment advice, and is not a recommendation to buy, sell, or hold any security.
Original reporting by The Globe and Mail. This article is desk analysis prepared by The Forensic Ledger from publicly available sources, summarized with citation to the original.
Not investment advice. This is original reporting and analysis prepared by The Forensic Ledger from publicly available data. Nothing here is a recommendation to buy, sell, or hold any security. Always consult the original source and a licensed professional. See our full disclaimer and source-citation policy.