Securities Fraud Investigation Into Guggenheim Strategic Opportunities Fund (NYSE: GOF) Continues After Short-Seller Report on Premium-Share-Funded Distributions
A law firm investigation into possible securities violations by Guggenheim Strategic Opportunities Fund (NYSE: GOF) is continuing, with shareholders who lost money urged to come forward. The investigation follows a short-seller report alleging that the fund's distributions were funded by selling shares at a premium — a circular structure that, if true, would mean investor distributions were effectively being paid for by new investor capital rather than underlying portfolio returns. The probe also unfolds against the backdrop of a federal investigation into Guggenheim CEO Mark Walter, adding a governance dimension to the fund-level disclosure questions.
Epistemic note. A law firm investigation is a preliminary step that may or may not result in a filed action, and a short-seller report represents the analyst's allegations rather than established fact. The Forensic Ledger is reporting on the existence and substance of both, not adopting their claims as proven. Guggenheim and Mark Walter are entitled to dispute the allegations, and no adjudication has occurred.
The premium-share-funded distribution thesis
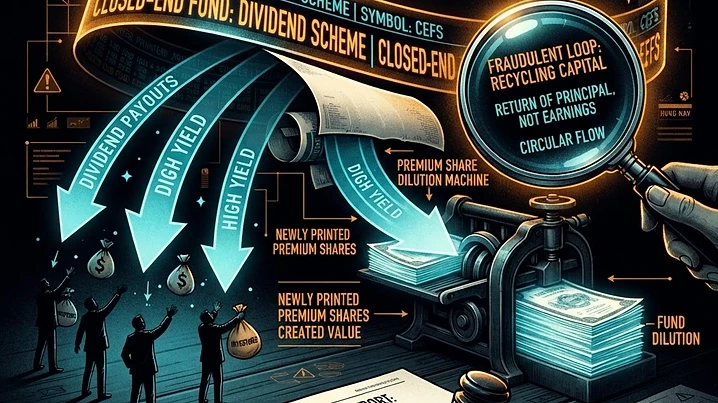
The short-seller report at the center of the investigation alleges a specific and serious mechanism: that Guggenheim Strategic Opportunities Fund's distributions were funded not by investment income or realized portfolio gains, but by selling shares at a premium to net asset value. Closed-end funds frequently trade at premiums or discounts to NAV; the allegation here is that GOF's premium-trading share price was used to issue new shares — capturing the premium spread — and that the proceeds were then routed into distributions to existing shareholders. If true, the structure would mean distributions were being financed by dilution rather than portfolio performance, a fundamentally different economic reality than the one investors would reasonably infer from a distribution yield.
Why the mechanism is load-bearing
A distribution funded by selling premium shares is not income. It is, mechanically, a transfer from new subscribers to existing holders — one that can sustain the appearance of a high-yield vehicle while eroding the per-share economics of the fund. The forensic significance is twofold. First, the source of distributions is a material disclosure item: investors pricing a yield vehicle are entitled to know whether that yield is underwritten by portfolio returns or by capital structure mechanics. Second, the premium-trading dynamic is self-reinforcing as long as new share issuance at premium continues — a structure that, if alleged correctly, raises questions about the sustainability of both the premium and the distribution once the issuance channel is constrained.
The Mark Walter federal investigation context
The fund-level investigation does not exist in isolation. It unfolds against the backdrop of a federal investigation into Guggenheim CEO Mark Walter, a governance overlay that compounds the disclosure questions around GOF. Where a fund's distribution and issuance practices are under scrutiny at the same time as the ultimate parent's chief executive is the subject of a federal probe, the combined picture is one of layered governance and disclosure risk — precisely the constellation of facts that securities investigations are designed to examine. The Forensic Ledger reports this context without conflating the two matters, which are distinct in subject and scope.
What would falsify the thesis
Falsification would look like: Guggenheim demonstrating that GOF's distributions were funded by portfolio income and realized gains rather than premium-share issuance, with the premium spread on any issuance properly disclosed and immaterial to the distribution; the law firm investigation not resulting in a filed action or being resolved on terms that do not materially impair the fund; the short-seller report's allegations being rebutted with auditable distribution-source disclosures; and the federal investigation into Mark Walter concluding without findings material to Guggenheim or GOF. Corroborating developments would include disclosure of premium-share-funded distribution mechanics, NAV or distribution guidance revisions, regulatory scrutiny of the fund's issuance and distribution practices, additional class actions or investigations, or governance changes at the fund or parent level.
Source
⚖️ Editorial Disclaimer
This article is original reporting by The Forensic Ledger Desk on an ongoing law firm investigation and a short-seller report. A law firm investigation is a preliminary step that may not result in a filed action, and a short-seller report represents the analyst's allegations rather than established fact. The Forensic Ledger is an independent newsroom and does not adopt the investigation's or the short-seller's claims as proven; Guggenheim and Mark Walter are entitled to dispute them, and no adjudication has occurred. This article is published for informational and journalistic purposes only, is not investment advice, and is not a recommendation to buy, sell, or hold any security.
Original reporting by WBOC. This article is desk analysis prepared by The Forensic Ledger from publicly available sources, summarized with citation to the original.
Not investment advice. This is original reporting and analysis prepared by The Forensic Ledger from publicly available data. Nothing here is a recommendation to buy, sell, or hold any security. Always consult the original source and a licensed professional. See our full disclaimer and source-citation policy.